
Home › What Insurance Does a Commercial Cleaning Company Need?
What insurance does a commercial cleaning company need?
Most commercial cleaning companies start with general liability, a janitorial bond and workers' comp, then add auto, crime and higher limits as contracts get bigger. Here's what each policy does and when it usually comes into play.
The short answer for a commercial cleaning company
If you clean other people's buildings, your clients will usually ask for proof of general liability before your first shift, and many will ask whether you're bonded. Once you have employees, most states require workers' comp. After that, the coverages you add track the contracts you win: a van and crews driving between sites, a portfolio that wants a $2 million umbrella, a client who hands you master keys. The groups below follow that order.
The core three
General liability
Pays for injuries and property damage your work causes to others, like a slip on a floor your crew just mopped, subject to the policy's terms. General liability for cleaning businesses
Janitorial bonds
A bond your client can claim against if one of your employees steals from them. Many contracts ask for one by amount. How janitorial bonds work
Workers' comp
Pays an injured crew member's medical care and part of their lost pay. It's required in most states when you hire, though some states only require it above a set number of employees. Workers' comp for cleaning crews
Gaps that catch cleaning companies off guard
Client property and lost keys
Liability policies often limit coverage for property in your care, and few include re-keying a building when a master key goes missing. Client property and lost key coverage
Employee dishonesty and crime
First-party crime coverage protects your own money and can extend to clients' property. It isn't the same thing as a janitorial bond. Crime coverage for cleaners
Pollution and chemical liability
Fumes or a chemical spill can run into a pollution exclusion on a standard liability policy. Chemical liability coverage
Coverage that grows with your contracts
Commercial auto and hired/non-owned auto
For company vans, and for crew members who drive their own cars between buildings. Auto coverage for cleaning companies
Umbrella
Extra liability limits above your GL, auto and employer's liability when a contract asks for $2 million or more. Umbrella insurance
Equipment and tools
Covers floor machines, extractors and vacuums, including equipment you store in a client's janitor closet. Equipment coverage
Also worth a look
Business owner's policy
Bundles liability with property coverage for your office and supplies, if your company qualifies. BOPs for cleaning companies
Employment practices liability
Covers claims like harassment or wrongful termination, which come up more often in high-turnover workforces. EPLI for cleaning companies
Cyber liability
Helps with data breaches, payroll data exposure and invoice fraud. Cyber coverage
Coverage by the buildings you clean
The facilities on your route change what underwriters ask and what clients require.
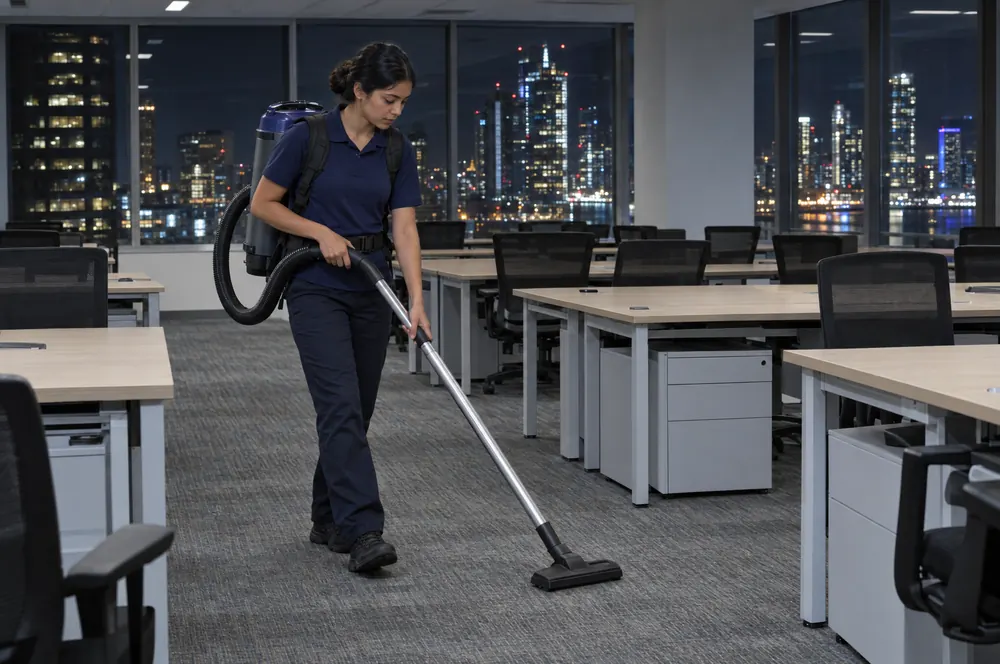 Office & janitorial servicesNight crews, day porters and multi-tenant buildings.
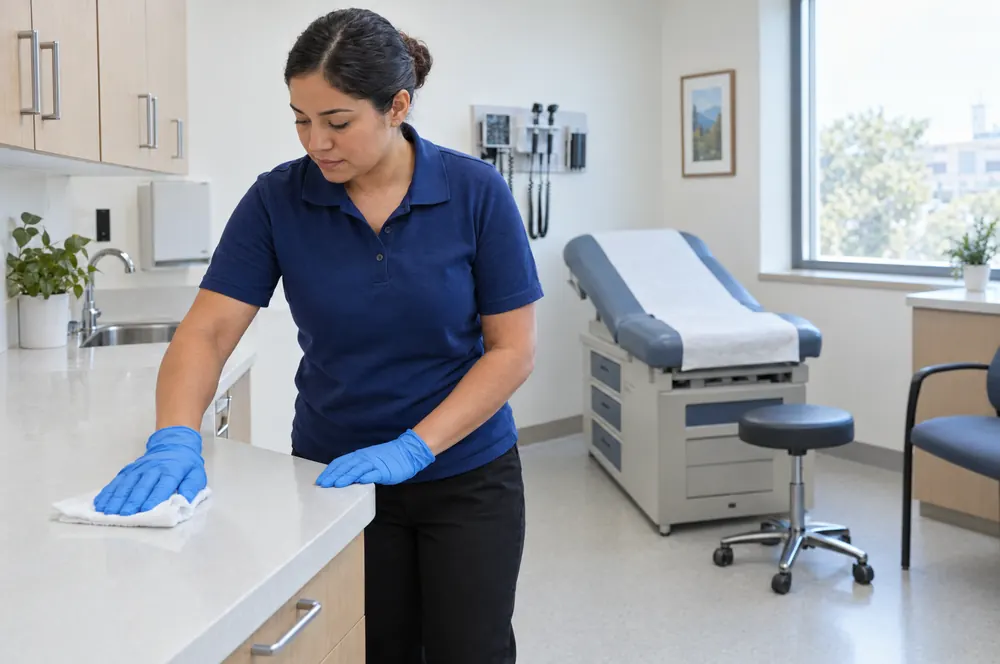 Medical offices & clinicsMore disinfectant use and stricter protocols.
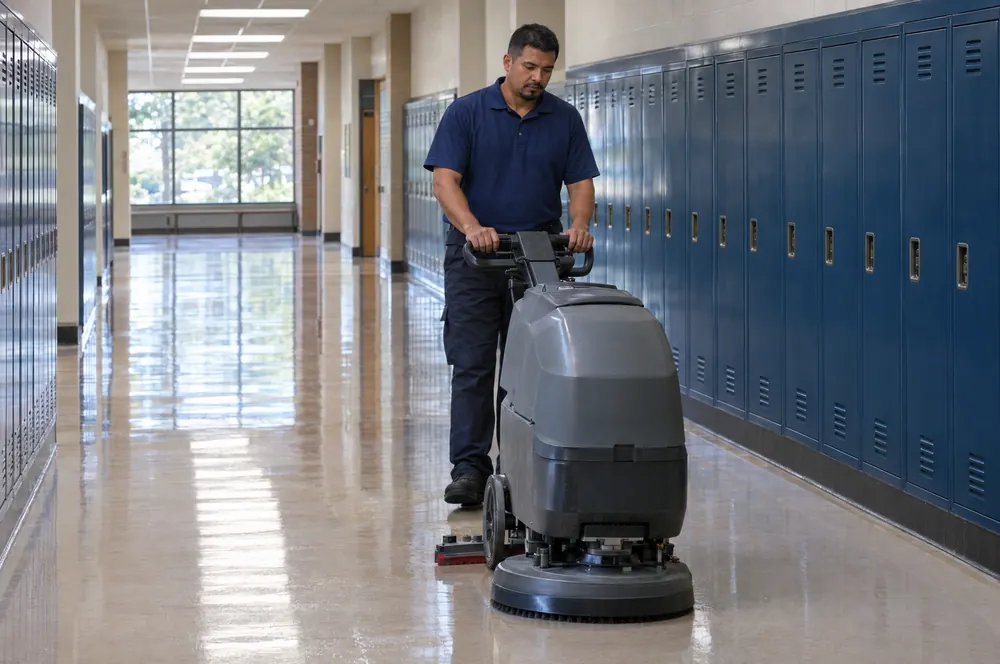 Schools & campusesDistrict contracts with set limits and background checks.
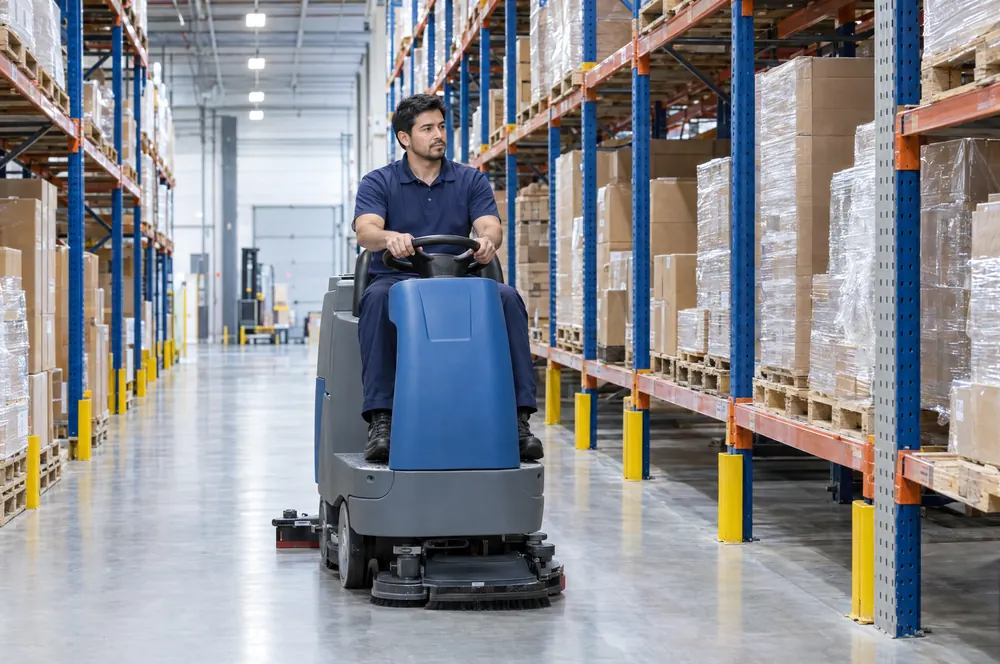 Industrial & warehousesHeavier equipment and plant safety rules.
 Carpet, floor & window cleaningSpecialty services with their own equipment and surface risks.
 Cleaning franchise ownersFranchise agreements that set your minimums.
Coverage questions
What insurance does a commercial cleaning company need?
Is a janitorial bond the same as insurance?
My crew is all part-time. Does workers' comp still apply?
Does general liability cover damage to a client's floor or furniture?
Ready to see what you'd pay?
Independent agents, 12+ A-rated carriers, and a licensed agent back to you within one business day.